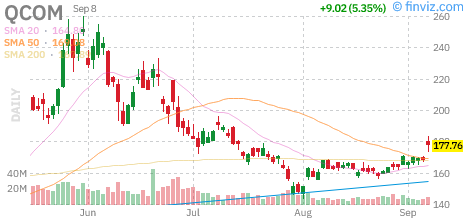
On September 8 (U.S. time), Qualcomm (QCOM) shares surged roughly 5%, moving from the previous close of $168.74 into the upper $170s. Trading volume has run above recent averages. The move followed Amazon's announcement that Qualcomm would develop custom data-center chips alongside Amazon Web Services—and that Qualcomm is granting Amazon warrants to purchase up to 25 million shares at $161.26 per share as part of the deal.
This is more than a single buyer-flow event. It signals that the world's largest cloud provider has chosen Qualcomm as a silicon partner.
Why did Amazon grant Qualcomm this warrant?
The two companies will co-develop custom silicon across multiple generations for Amazon Web Services' large-scale AI data centers, with a focus on inference—the computational task of running a trained AI model in production. They will also jointly develop 1.6 terabit-class optical interconnect technology. Qualcomm is applying the low-power chip design expertise and optical DSP capabilities it built in the smartphone market to the data-center space.
In return, Qualcomm granted Amazon warrants for up to 25 million shares at $161.26 per share, with an expiration date of September 2036—a 10-year term. The industry estimates the total contract value at up to $60 billion as commercial commitments scale.
Will data-center silicon actually move the needle for Qualcomm?
Qualcomm CEO Cristiano Amon said: "As AI demand accelerates, data-center infrastructure demands advances in both computing and connectivity." AWS Vice President Prasad Kalyanaraman added: "By developing custom silicon and advanced connectivity together, we can deliver infrastructure that is more performant, efficient, and cost-effective to customers."
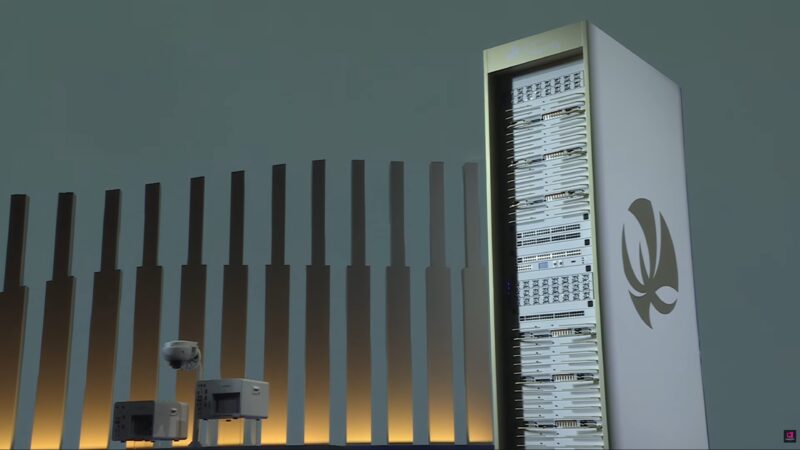
Qualcomm is historically a smartphone-chip company. It has spent several years broadening into automobiles, IoT, and data centers. Landing Amazon—the world's largest cloud operator—as a customer validates this expansion strategy in the clearest possible way. Meta already committed in June to using Qualcomm's new data-center CPU, Dragonfly. Now Amazon has joined.
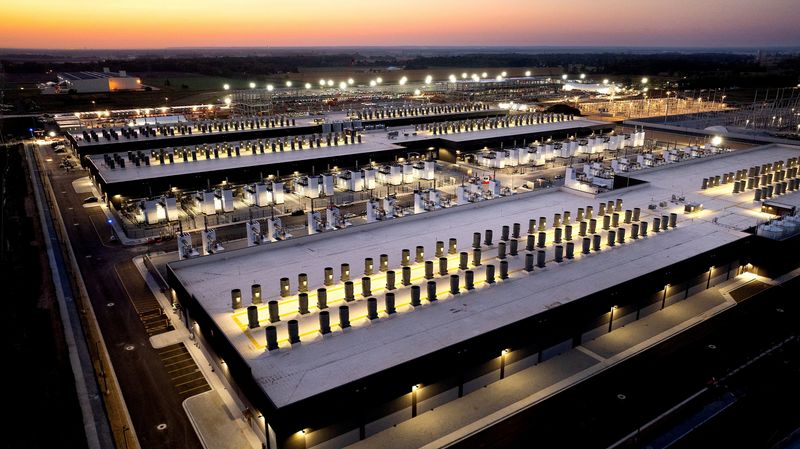
Yet NVIDIA remains the dominant force in this market, having captured the vast majority of the GPU-based AI training and inference space. Qualcomm enters as a latecomer from a narrower channel: low-power, inference-focused silicon. The dynamics of competition with NVIDIA, manufacturing constraints, supply-chain economics, and how Amazon's internally developed chips like Trainium fit into the picture all bear watching.
The stock had lagged while the rest of the sector surged
That context makes today's gain more notable. The Philadelphia Semiconductor Index (PHLX) is up 68% year to date. Qualcomm has trailed that performance significantly. While AI leaders like NVIDIA and Broadcom have accelerated higher within the same sector, Qualcomm has been held back by the persistent label of smartphone-market maturity.
That frames today's move differently. It may be the moment the market first takes seriously the idea that Qualcomm can expand into AI data centers. But no revenue has yet been recognized. The company has guided to $15 billion in data-center AI revenue and $40 billion in non-handset revenue by fiscal 2029—three years out.
| Item | Details |
|---|---|
| Announcement date | Early September 2026 (U.S. time) |
| Stock reaction | Previous close $168.74 → surged roughly 5% to upper $170s |
| Warrant terms | Up to 25 million shares, exercise price $161.26, expiration September 2036 |
| Estimated deal value | Up to $60 billion (industry estimate) |
| Core technology focus | Custom inference silicon for AI, 1.6 terabit-class optical interconnect |
Where does Qualcomm stand now?
By today's action, this is a single-stock catalyst. The market responded to one concrete fact: Qualcomm has secured Amazon as a major customer. Yet the warrant strike price is $161.26—below today's level. Even Amazon has structured room to build its stake at a lower price point. That suggests the market is not viewing this as pure upside revaluation.
The next meaningful test comes with quarterly earnings. That is when this partnership first shows up in revenue. The company has publicly committed to $15 billion in data-center AI revenue by fiscal 2029. How quickly that figure rises toward the target each quarter will reveal whether today's surge was a momentary pop or a genuine inflection point.
For years it built infrastructure in NVIDIA's shadow. Today it received the market's spotlight. Now it must prove through numbers that the foundation is solid.
U.S.-listed stock. This is factual analysis, not a buy or sell recommendation. All investment decisions and results are the reader's responsibility.
#Qualcomm #QCOM #QCOMstock #USstocks #Amazon #AWS #AI #datacenter #semiconductors #Nasdaq #warrant #Amon #inference #NVIDIA #Broadcom #Meta #Dragonfly #USmarkets #StockInFocus #semis
댓글
댓글 쓰기