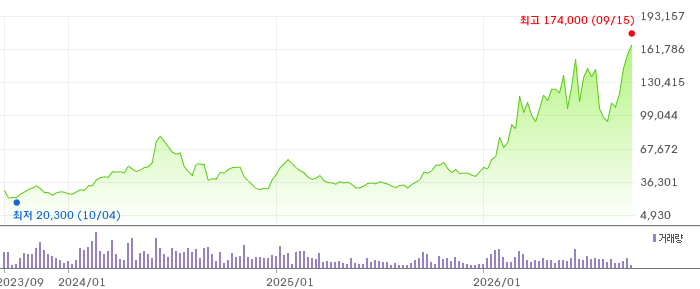
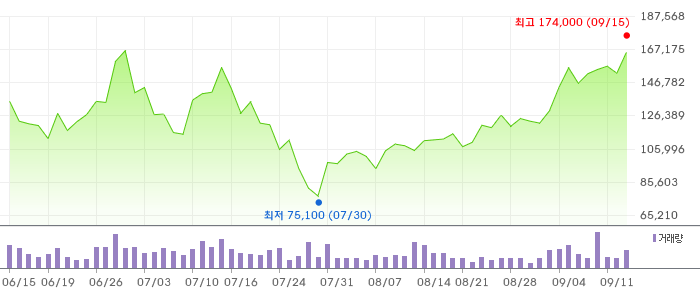
PSK Holdings shares closed at 166,500 KRW on September 15, up 7.1% for the day and marking a new 52-week high. The move lifted the company's market capitalization to 3.57 trillion KRW.
The timing is unusual. Over the past three months, semiconductor equipment rivals have fallen broadly. PSK, alone among them, has climbed.
Divergence in a declining sector
The three-month performance gap is stark. Samsung Electronics down 29.5%, SK Hynix down 38.6%, Hanwha Semiconductors down 24.2%, Wonik IPS down 29.4%, Solbrain down 10.5%—the sector median is -29.4%. All down. PSK, meanwhile, is up 48.0% over the same span.
Expand to one year, and the picture doesn't change. Samsung up 259%, SK Hynix up 521%, yet PSK ahead at 356%, with amplified swings throughout. The sector has wobbled; this stock has moved against the tide. The reason lies within the company, not the cycle.
Earnings tell a different story
Last year was unspectacular by design. 2025 revenue came to 207.8 billion KRW, operating profit 73.4 billion KRW—a 17.1% decline from the prior year, a tough comparison after 2024's strength.
This year reversed course. First half 2026: combined revenue of 206.5 billion KRW (Q1: 111.9 billion, Q2: 94.6 billion), enough to nearly match all of 2025 in just six months. More striking: Q2 operating profit hit 27.6 billion KRW, up 63.3% from the prior year and well ahead of the analyst consensus estimate of roughly 18.3 billion KRW.
PSK manufactures two product lines: disc-cleaning equipment that removes residue from semiconductor packaging, and reflow equipment that evens bump-joining during assembly. Both are essential when multiple layers of high-bandwidth memory (HBM) are stacked, and both are critical to advanced co-packaged processors (CoWoS) deployed by foundries like TSMC. Within South Korea, PSK is the sole equipment vendor supplying all three major HBM manufacturers: Samsung Electronics, SK Hynix, and Micron.
One clarification is warranted: Q1 net income reached 80.2 billion KRW and Q2 net income 48.8 billion KRW, both substantially larger than operating profit (36.7 billion and 27.6 billion KRW, respectively). Non-operating items appear to have lifted net profit, though publicly disclosed details do not clarify the specific drivers. For this reason, we reference operating profit rather than net income.
Valuation in context
Current valuations stand at 39.1x forward P/E and 7.1x P/B. Both exceed the semiconductor sector average (Samsung 37.8x P/E, SK Hynix 28.6x)—though remain below Hanwha Semiconductors at 99.4x. Premium multiples are routine for packaging equipment suppliers.
KB Securities set a July price target of 220,000 KRW, implying 32% upside from today's close. The thesis rests on operating profit growth of 45% expected for 2026. A higher target than current price signals that at least one major broker does not regard today's valuation as stretched.
Target prices, however, depend on forecasts being accurate. The assumption here is continuous: HBM and CoWoS capacity expansion proceeds at its current pace. If that premise breaks, a 39x P/E can turn hostile quickly.
The watch point ahead
A company's stock climbing to new highs while its sector retreats is always instructive. Here, earnings growth is the anchor. Operating profit is demonstrably expanding, and the figures are fresh.
The next test will come in late October or early November when Q3 results are expected. Hanwha Securities has estimated Q3 operating profit at 35.0 billion KRW, a 154% increase from Q2. Whether that number materializes—and whether it justifies the current valuation—will be the measure.
When a stock holds ground while its peers falter, two explanations apply: either the company is genuinely different, or it harbors undisclosed risks the market has yet to price. So far, the earnings record points to the former.
This article is provided for informational purposes and does not constitute a recommendation to buy or sell any security.
#PSKHoldings #031980 #SemiconductorEquipment #HighBandwidthMemory #HBM #CoWoS #PackagingEquipment #TSMC #SamsungElectronics #SKHynix #Micron #KRXEquipment #NewHigh #FY2026
댓글
댓글 쓰기