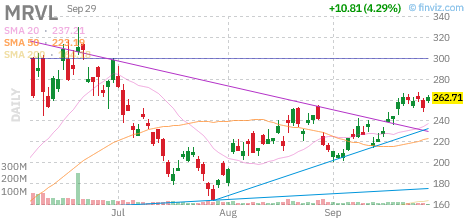
As of 2:31 p.m. ET on September 29, Marvell Technology (MRVL) was trading at $262.83, up from the prior close of $251.90. That's a 4.34% gain. The stock topped $263 intraday, with the market still open at time of writing.
It was a day for the whole semiconductor sector. Marvell also got its own catalyst. Both deserve attention.
Sector-wide rebound
The semiconductor index jumped roughly 4%. AMD surged over 6%, and Marvell rode the same wave. Recent concerns about pacing in AI-related stocks had pulled flows out of semiconductors; today, those dollars moved back in.
In other words, today's gain wasn't Marvell-specific. The entire sector moved together. The rebound was sector-wide recovery rather than company-driven strength.
Analyst target hike
Marvell got one catalyst of its own: Canter Fitzgerald raised its price target to $330 from $300 on September 28. Analyst C.J. Mutz kept the rating at neutral while lifting the target.
The reason is October 6, when Marvell holds an investor day focused on custom silicon. Canter sees the event as a chance for the company to reframe the data-center addressable market at as much as $625 billion. The firm projects custom-silicon revenue could grow 40-45% annually from 2025 through 2030.
The numbers are large on paper. These are projections—one analyst's calculations. What Marvell actually reveals on October 6 remains to be seen.
The Google backdrop
The investor day has extra weight because of August news: Google expanded its custom-silicon deal with Marvell. The terms are unusual. Google received warrants to buy roughly 59 million Marvell shares at $206.58 per share, but those rights unlock only as Google actually purchases Marvell's custom chips. The contract runs through fiscal 2033.
Broadcom has long been Google's sole supplier for custom silicon, including the company's TPU (tensor processing unit) designs. Today's expansion makes Marvell a second supplier. But this was August news. Today's gain wasn't driven by that announcement—rather, it set the stage for Investor Day expectations.
What the company is actually generating
Data center now accounts for roughly 79% of Marvell's revenue. The company has essentially transformed into a data-center play. That segment's revenue has grown over 40% in the past year.
Custom silicon alone is roughly a $1.5 billion annual business. It represents about 18% of revenue today, but Marvell projects over 20% growth next year (FY27) and more than double that growth the year after (FY28). The company says it has programs in place with all four major hyperscalers.
The catch is valuation. At current levels, the stock trades at an 80x P/E multiple—not cheap.
| Item | Value |
|---|---|
| Current price (Sept. 29, intraday) | $262.83 |
| Prior close | $251.90 |
| Canter Fitzgerald target | $330 (prior $300) |
| P/E multiple | Approximately 83x |
| Data-center revenue mix | Approximately 79% |
The risk
An 83x P/E multiple is difficult to justify as cheap. If earnings miss expectations, the downside could be equally sharp. The stock has more than doubled this year, so investor-day expectations are running high.
The Google warrants are not without risk. They remain unexercised if Google does not buy the chips. This is a conditional deal that Marvell must earn through execution. And Broadcom remains an entrenched competitor in the same space.
Bottom line
Today's gain appears to blend sector-wide recovery with Canter's pre-event momentum. The company did not prove new strength today. That proof comes October 6 at the investor day.
The next inflection point is clear: October 6. What matters is how specific Marvell's custom-silicon revenue targets and roadmap turn out to be. If the numbers fall short of Canter's projections, the stock could give back today's gains.
High-valuation stocks live by execution. Marvell's test arrives in less than a week.
Marvell is U.S.-listed. This is factual reporting, not investment advice. Investment decisions and outcomes are the reader's responsibility.
#Marvell #MRVL #USstocks #semiconductors #AIchips #customsilicon #datacenters #Google #CinterFitzgerald #investorday #Nasdaq #USmarkets #semiconductorsector #AIinfrastructure #hyperscalers #pricingtarget #StockInFocus #equitynews #overseasstocks #chipstocks
댓글
댓글 쓰기