As of September 2026. Your Korean national pension claim age depends on your birth year. First, find when you're eligible. Then, consider early claiming. Let's work through whether claiming early makes sense for you.
When can I claim, based on birth year?
The Korean national pension system did not raise claim ages all at once after a 1998 law change. It phased them in gradually by birth year. That's why your parents' generation has a different claim age than people in their 40s today—sometimes 5 years apart.
| Birth Year | Full Retirement Age | Earliest Claim Age |
|---|---|---|
| Before 1952 | 60 | 55 |
| 1953–1956 | 61 | 56 |
| 1957–1960 | 62 | 57 |
| 1961–1964 | 63 | 58 |
| 1965–1968 | 64 | 59 |
| 1969 and later | 65 | 60 |
For those born 1969 or later, 65 is the full retirement age. If you're in your early-to-mid 40s now, that likely applies to you. The earliest claim age is five years before your full retirement age, and this relationship holds across all cohorts.
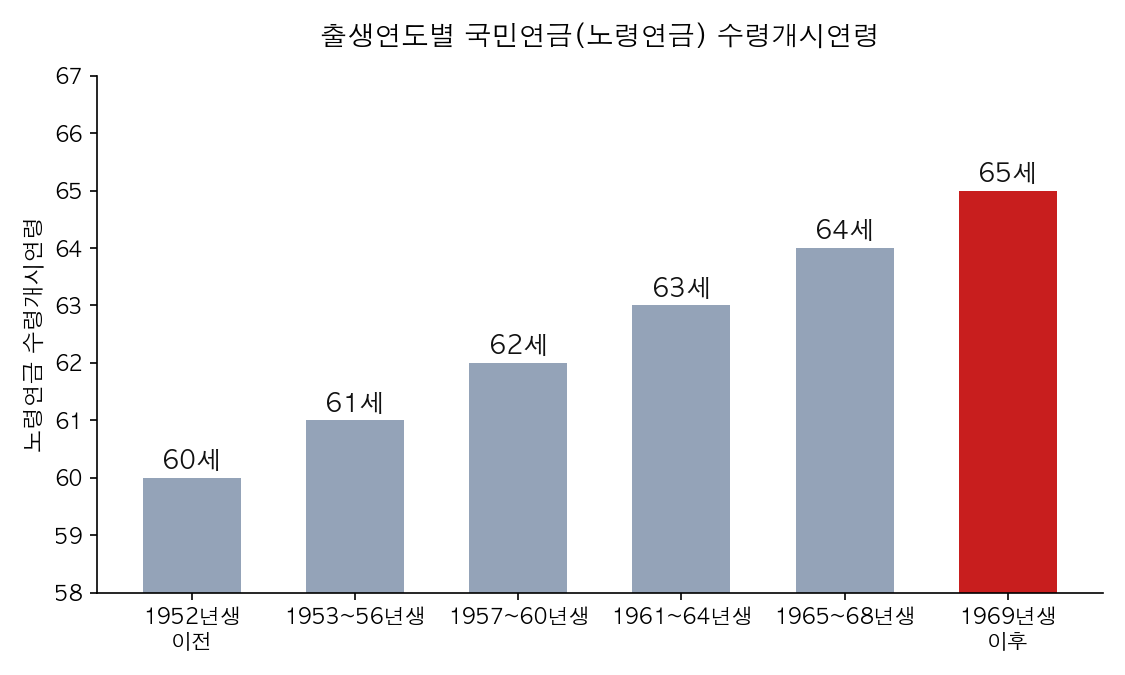
Compiled by author (National Pension Service)
Old-age pension benefit is not the same as "national pension"
This trips up a lot of people. The National Pension Service is the program name. Old-age pension benefit is the official term for the retirement payment. Within the National Pension system, there are also disability and survivor benefits. When people say they're "claiming their national pension," they usually mean the old-age benefit.
So "early old-age pension claim age" and "early national pension claim age" are the same question. The Basic Pension is different—it's a separate program entirely. The Basic Pension is government assistance paid to those 65 and older with income below the 70th percentile. You can receive both your old-age pension benefit and Basic Pension at the same time. However, if your old-age pension benefit exceeds a threshold, your Basic Pension amount is reduced.
How much less do you get if you claim 5 years early?
Claiming before your full retirement age is called early old-age pension claiming. The National Pension Service sets three conditions.
You need at least 10 years of contribution history. You must reach your earliest claim age (right column of the table above). At the time of application, your average monthly income must not exceed the 2026 National Average Wage Index of KRW 3,193,511. This third condition is often overlooked by the self-employed or those re-entering the workforce.
| Years Early | Reduction in Monthly Benefit |
|---|---|
| 1 year | −6% |
| 2 years | −12% |
| 3 years | −18% |
| 4 years | −24% |
| 5 years (maximum) | −30% |
Your benefit drops 6% for each year you claim early. The maximum advance is 5 years. At the steepest, you'll receive 30% less than your full benefit amount. This 30% reduction is permanent. Once set, it doesn't return to the full amount even after you reach your full retirement age.
The opposite option exists too: delayed claiming. For each year you wait past your full retirement age, your benefit rises 7.2% annually, up to 5 years (36% total). The delayed-claiming bonus is somewhat more generous than the early-claiming penalty.
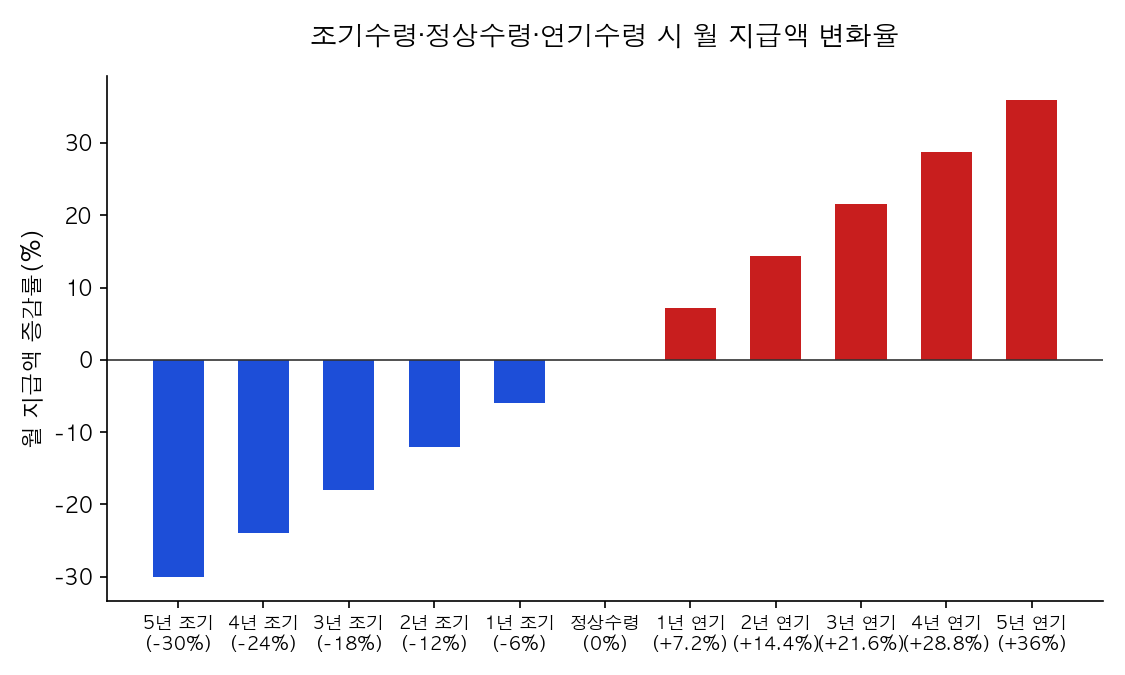
Compiled by author (National Pension Service)
Who should claim early and who shouldn't
There's no single right answer. It depends on your circumstances. If health issues or family history suggest a shorter life span, the calculation changes. A smaller monthly payment might yield higher lifetime income if you collect for more years.
If you expect to work or have other income after stepping back, early claiming becomes complicated. The income limits apply at time of application. There's also a separate rule: if you have other income after reaching full retirement age, your benefit is reduced for a specified period. If you're confident in your health and longevity, delayed claiming merits consideration.
The breakeven point is roughly a decade. Whether you live about 10 years beyond your full retirement age determines the winner. Even with the steepest 30% cut, compared to your full benefit, lifetime income is designed to be roughly comparable if you reach average life expectancy. So the real question is not "how long will I live?" but rather "do I need the cash now?"
What to confirm before you apply
If your contribution history falls short of 10 years, early claiming is unavailable. You can extend your record through continued voluntary contributions. Your exact contribution history and estimated benefit are available instantly on the National Pension Service website or via the My National Pension mobile app.
Because rules and amounts can change, before you apply, verify the latest criteria at the National Pension Service (nps.or.kr) or call 1355 (no area code).
This article provides information about the National Pension system and does not recommend any particular choice. Your financial decisions and their outcomes are your own responsibility.
댓글
댓글 쓰기