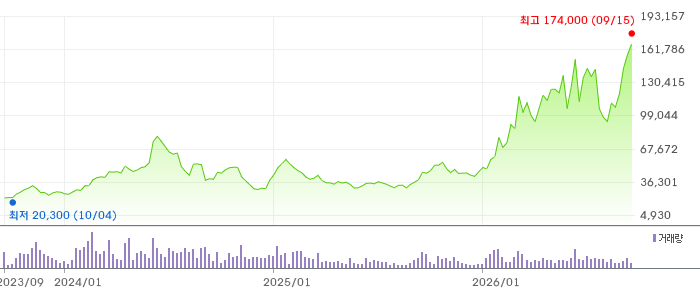
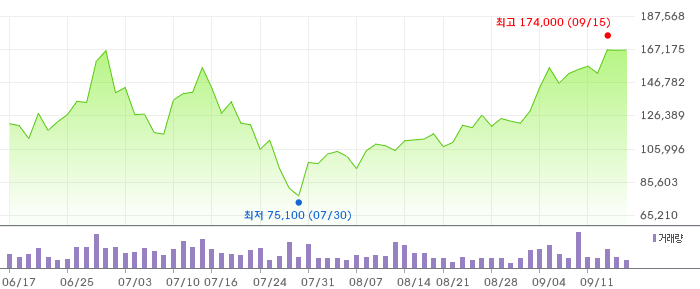
PSK Holdings closed at 166,902 won on September 17. That's a 42% gain over three months.
Over the same stretch, Samsung Electronics dropped 17.7%, SK Hynix fell 31%, and Wonik IPS—the bellwether of chip-equipment stocks—was down 20.8%. The sector was retreating. This one moved the opposite way.
The Sector Retreats While PSK Advances
Three-month performance across the Korean semiconductor complex:
· Samsung Electronics -17.7% · SK Hynix -31.0% · Hanmi Semiconductor -11.8% · Wonik IPS -20.8% · Solbreain -1.3%
The peer median is -17.7%. PSK stands alone at +42.0%. A gap that wide doesn't reflect sector dynamics—it points to something specific to the company.
Over a full year, both rode the same wave: SK Hynix soared 512% and PSK climbed 337%. But the past quarter has clearly diverged.
What the Company Makes
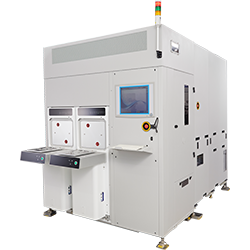
PSK builds ashing equipment—machines that burn off photoresist residue left on semiconductor wafers after patterning. It commands a 41% global market share, the industry's largest, and was Korea's first domestic supplier.
Today's price driver isn't ashing. It's a different product. HBM stacking uses a thermal-compression bonding step that leaves residue, which requires reflow and plasma-cleaning equipment to remove. As HBM layer counts rise from 12-stacked to 16-stacked configurations, these cleanup steps account for a larger share of the process. More layers mean more processing steps.
But Last Year's Earnings Fell
Here's where it gets interesting: FY2025 revenue fell 17.1% to 207.8 billion won, with operating profit down to 73.4 billion won. Earnings retrenched. Yet the stock tripled in the interim.
The market isn't looking backward at last year's numbers. It's pricing in what comes next. Hana Securities' September 11 report pegged Q3 revenue at 82.5 billion won and operating profit at 35.0 billion won—up 74% and 154% sequentially. The reason is straightforward: CoWoS-related equipment orders delayed from the prior quarter are now flowing through. Q4 is forecast to exceed 100 billion won in quarterly revenue—an all-time high.
How the Street Values It Today
Shinhan Investment raised its target price from 135,000 won to 210,000 won—a 55% bump. Hana Securities targets 220,000 won, reaffirming buy. Both sit above today's 166,902 won price by 25%-32%.
Analyst targets above current price mean the street doesn't view it as expensive. But today's P/E sits at 39x. That's on par with Samsung Electronics at 38.9x but higher than SK Hynix at 29.9x—despite SK Hynix's stronger growth rate. PSK's valuation hinges on earnings arriving as forecast.
What to Monitor
The company serves 60-plus customers, including Samsung Electronics, SK Hynix, and TSMC—no concentration on a single account. Debt-to-equity runs a lean 15%-21%, and liquid assets exceed 150 billion won.
Risks exist: semiconductor equipment revenue is hostage to customer capex schedules. Last year's earnings decline reflected just such a spending pause. If HBM 16-layer transitions or CoWoS expansions slip, the story shifts. Any hiccup in Q3-Q4 execution will shake the expectations already priced in.
The Bottom Line
This is a company whose earnings contracted last year. It's climbing to new highs while peers retreat—because thicker HBM stacks mean more need for PSK's equipment, and that demand is already showing up in Q3 figures.
What to watch narrows to one number: Hana Securities' Q3 operating-profit forecast of 35.0 billion won. The key is whether actual October disclosure matches that estimate. If it does, today's valuation holds. If it misses, the 42-percentage-point advantage over peers could retrace quickly.
Until earnings land, the spread between analyst estimates and actual disclosure will define the narrative.
This article is for informational purposes and does not constitute investment advice or recommendations to buy or sell any security.
#PSKHoldings #031980 #ChipEquipment #HBM #CoWoS #Ashing #BackendProcess #ReflowEquipment #PlasmaCleaning #NewHigh #SemiconductorStocks #KOSDAQ #HanaSecurities #ShinhanInvestment #TargetPrice #SemiconductorInvesting #Wafer #PackagingEquipment #Capex #ChipCycle
댓글
댓글 쓰기