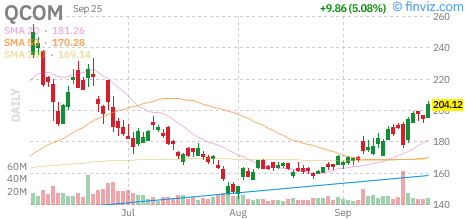
Qualcomm (QCOM) stock jumped 5.08% in today's U.S. trading, reaching around $204.13. The rally that started last week extended into today. Over the past month alone, the stock has already climbed more than 14%.
Behind the move: a convergence of three catalysts. Apple renewed its global patent license agreement. Qualcomm unveiled new Snapdragon flagship processors. Amazon signed a major custom semiconductor deal. All three events hit within days.
Apple is back, but initial reaction moved the opposite direction
On September 24, Qualcomm announced it had renewed its global patent license agreement with Apple, effective April 1, 2027. Apple will continue to use Qualcomm's wireless-communications patents, and Qualcomm will continue to receive royalties.
Notably, the stock initially declined following the announcement. Then, a day later, buying pressure returned. The reversal was sharp: on September 25 alone, the stock jumped 6% to $205.21. The market appeared to reassess concerns about losing Apple as a customer, replacing worry with relief.
Maui delivered new chips
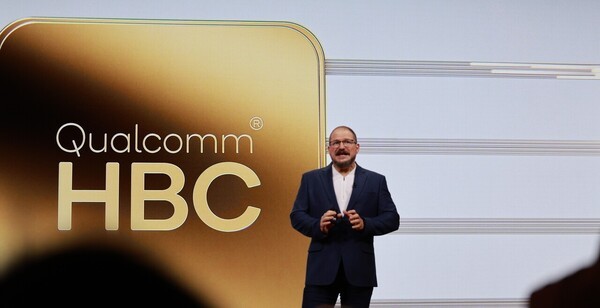
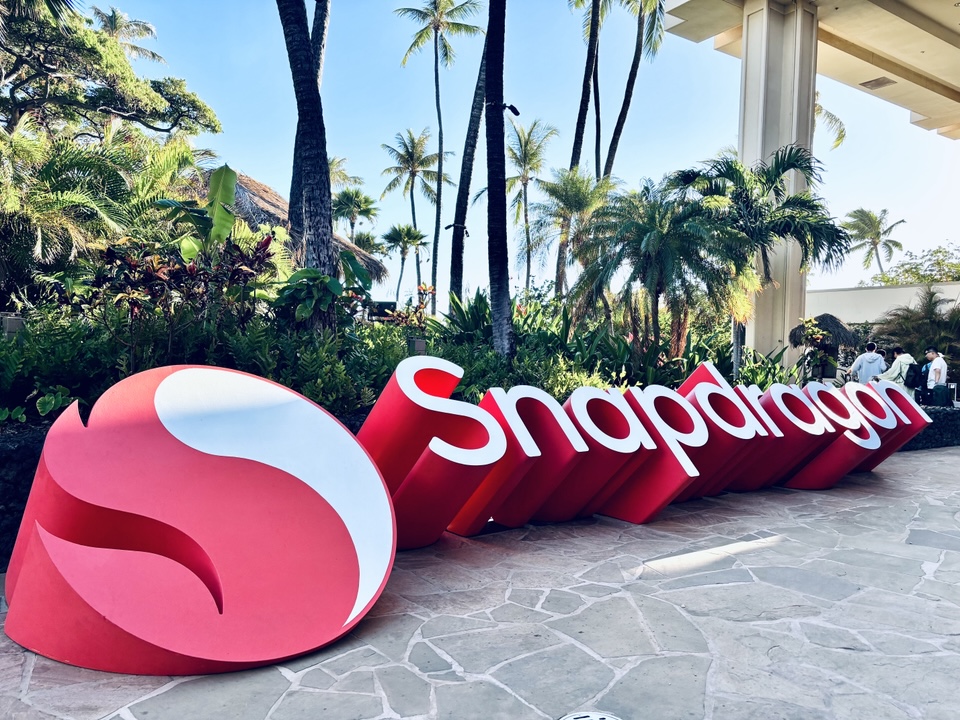
The same week, Qualcomm held its Snapdragon Summit in Maui, Hawaii, September 22-24. The company unveiled its next-generation flagship Snapdragon 8 Elite Gen 6 and the higher-end Extreme Gen 6.
On-device AI is the headline feature for both. A dedicated sensing hub runs models with up to 200 million parameters to automatically transcribe calls, distinguish speakers, and recall recent activities to inform next tasks. It is a smartphone story, but it represents datacenter technology migrated into the palm of a hand.
Amazon next—this one is worth $60 billion
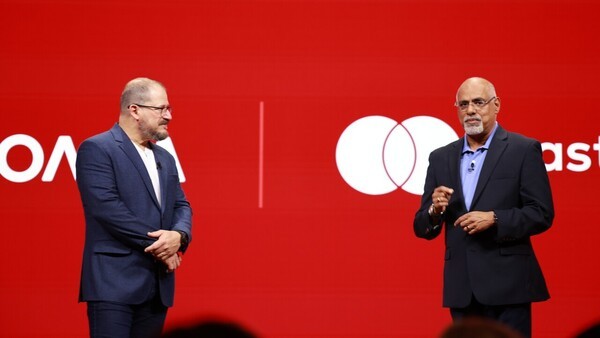
Adding to the momentum, the Amazon partnership announced earlier this month remains a key driver. Qualcomm will supply custom AI-datacenter semiconductors across multiple generations. Combined purchase commitments and payments could reach $60 billion at the high end.
Qualcomm has entered the datacenter market. The label "smartphone-chip company" no longer fully describes it. Revenue recognition is expected to begin in the December quarter, and some programs have already entered production.
But is all of this unambiguously good news?
Bernstein analyst Stacy Rasgon offered a different take on the Apple agreement. No specific terms—contract duration, royalty rates—were disclosed. As a result, the contribution to Qualcomm's earnings remains an estimate.
A separate concern: Apple continues to expand its own modem chip (C1). While Qualcomm may continue to collect license fees, the component volumes sold to Apple could shrink over time. Some analysts view the renewal less as a concern eliminated and more as a problem delayed.
What analysts are targeting
| Firm | Target Price | Notes |
|---|---|---|
| RBC Capital Markets | $180 | Raised from $160 after Amazon deal; neutral rating maintained |
| StoneX | $270 | Buy rating; watching expanded datacenter exposure |
| Street Average | ~$194 | Currently below market price |
The street average sits below the current price—a notable signal that valuation is a concern after the stock's recent run. Targets do shift, of course. RBC itself raised its target by $20 immediately after the Amazon announcement.
In the last quarter (fiscal 2026 Q3), Qualcomm reported $9.9 billion in revenue and non-GAAP earnings of $2.21 per share, matching guidance highs. Automotive revenue grew 61% year-over-year. The company is gradually shedding the "smartphone-chip company" label in the numbers.
Where Qualcomm stands now
Three favorable developments converged over a single week, creating a short-term rally. Apple risk did not disappear—it was deferred. The Amazon and datacenter opportunity remains at the expectation stage, before revenue appears in reported results. Yet the market has embraced the developments for now.
Two milestones to watch: when Apple's contract terms become specific, and whether Amazon revenue actually materializes in the December quarter. Until numbers arrive, this rally is only half-supported by concrete earnings visibility.
A U.S.-listed stock. This is factual analysis, not a recommendation to buy or sell. Investment decisions and outcomes rest with you.
#Qualcomm #QCOM #QualcommStock #USStocks #StockInFocus #Apple #Snapdragon #SnapdragonSummit #Amazon #AISemiconductors #DataCenter #SemiconductorStocks #Nasdaq #PatentLicense #PriceTarget #RBCCapitalMarkets #USMarkets #Semiconductors #OnDeviceAI #MobileChips
댓글
댓글 쓰기