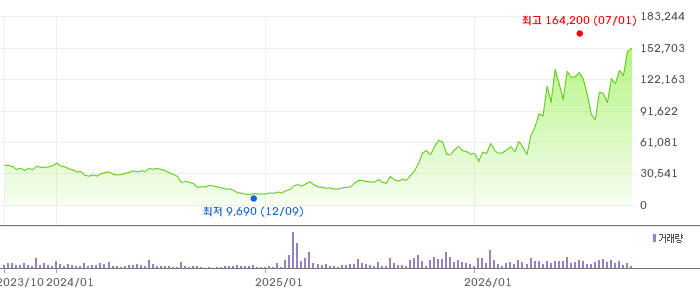
Simtex shares jumped more than 16% on a single day, September 22, closing at 148,100 KRW. As of September 29, the stock stood at 151,900 KRW, near its 52-week high.
Yet the stock's P/E ratio shows a negative 30.7x—shares are rising, but the earnings metric is in negative territory. The pieces don't seem to fit. Here's why, by the numbers.
Not a Solo Move
The September 22 surge wasn't unique to Simtex. On the same day, Korea Circuit jumped 26%, and Daeduk Electronics rose 12%. The driver: demand for AI server substrates. The entire PCB sector moved together that day.
But has momentum been evenly distributed recently? No. Over the past three months, Simtex is down 3.4%, compared to Daeduk Electronics down 14.8%, Korea Circuit down 16.8%, and Isupetasis down 11.0%. The median among three peers is negative 14.8%. Simtex alone held near flat.
Over a year, Simtex is up 366.7%, Daeduk Electronics 392.0%, and Korea Circuit 354.0%. The entire sector caught the AI substrate rally. But in the recent correction, Simtex has shown notably better resilience.
What Happened in the Second Quarter?
Start with the numbers. In the second quarter of 2026, Simtex posted revenue of 514.6 billion KRW and operating profit of 62.9 billion KRW. Operating profit surged 1,034% versus the same quarter last year—more than a tenfold jump.
Operating margin expanded to 12.2%, up from 3.25% in the first quarter—more than a threefold jump in a single quarter. Factory utilization climbed from 81% to 85%. Product mix also shifted. The improvement came from a higher share of higher-margin, value-added products like MSAP packaging substrates and SOCAMM, the company said.
For clarity: SOCAMM is a substrate for low-power DRAM modules used in AI servers. Simtex ranks among the largest suppliers of PCBs for SOCAMM and semiconductor packaging substrates. In other words, as AI server demand grows, Simtex's volumes rise in lockstep.
The 400 Billion KRW Investment and H2 Guidance
On September 2, Simtex signed a 400 billion KRW investment agreement with North Chungcheong Province and Cheongju City. Phase 1 capital commitment: 274.2 billion KRW for a new SOCAMM production facility and 100 new hires. The company is expanding manufacturing capacity to match AI chip demand.
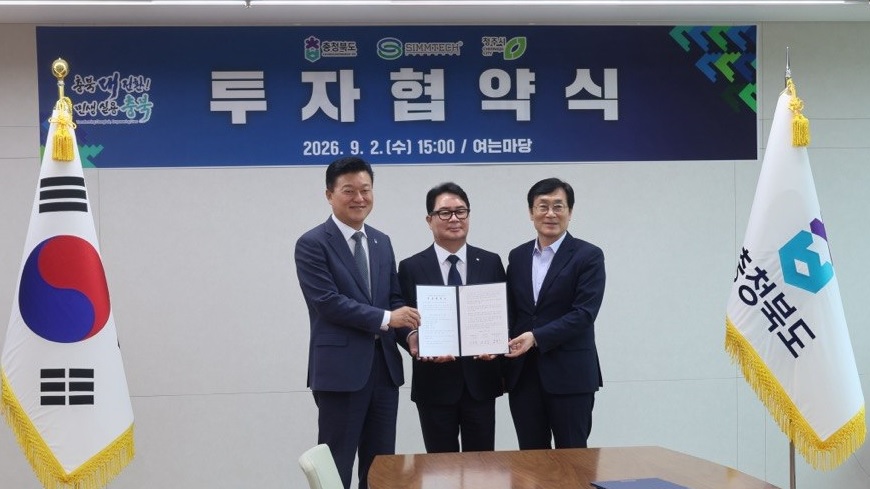
September 2 investment agreement signing in Cheongju
In a regulatory filing, the company guided for H2 revenue of 1.07 trillion KRW and operating profit of 163.1 billion KRW—a 113% increase in operating profit from H1. The stated drivers: growth in System IC-focused products, SOCAMM volume ramp-up, and improved high-margin product mix for AI. Note: these are company projections, not confirmed results.
Versus Competitors
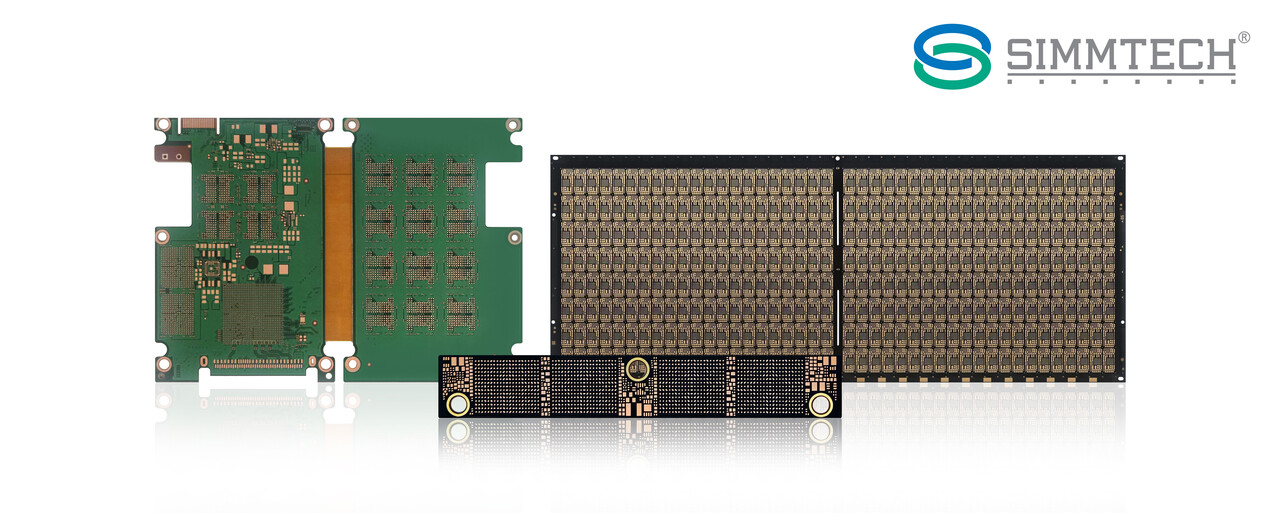
Simtex SOCAMM module substrate
Operating margins across peers vary sharply. Simtex 12.2%, Daeduk Electronics 4.6%, Korea Circuit 3.6%, Isupetasis 18.8%. Within the same PCB sector, spreads are substantial. Isupetasis centers on high-layer-count substrates, which naturally carry higher margins. Simtex, by contrast, has narrowed the gap only this quarter by tilting its product mix toward higher-margin items.
Back to the opening question: Why is the P/E negative? In 2025, Simtex returned to operating profit with 11.9 billion KRW but posted a net loss of 164.6 billion KRW. Operating results and bottom-line results diverged. Specific non-operating items behind this gap weren't confirmed in this review. But two facts stand out: the trailing P/E reflects last year's loss, and quarterly results in 2026 have shifted to a completely different trajectory.
Sell-side price targets diverge widely. IM Securities issued 185,000 KRW on June 8. Kyobo Securities put out 135,000 KRW in May. Earlier, in November, Korea Investment & Securities had 73,000 KRW. As earnings shift, target prices keep moving.
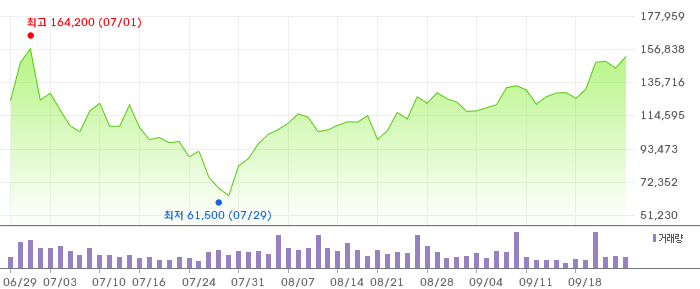
Where Does the Stock Stand?
A company deep in losses through 2025 has swung to dramatically different results riding 2026 AI server substrate demand. Even as the whole sector rallied, Simtex held up better during the recent selloff. The market appears to be pricing in the company's individual strength separately from the broader sector trend.
The next test is H2 results. The company has guided for 163.1 billion KRW in operating profit. Whether those numbers hold will emerge in the next quarter's report. A negative trailing P/E may give some pause, but this company is already tracing a different earnings arc.
This article is provided for informational purposes to support investment decisions and does not constitute a recommendation to buy or sell any security.
#Simtex #222800 #SimtexShare #SemiconductorSubstrates #PCB #SOCAMM #AIServer #SemiconductorMaterials #KOSDAQ #NewHigh #DaedukElectronics #KoreaCircuit #Isupetasis #PackagingSubstrates #CapitalExpansion #Cheongju #MSAP #AIChips #EarningsSurprise
댓글
댓글 쓰기