Dell (DELL) climbed 3% intraday on the morning of September 25, trading at $552.96 at 9:46 a.m. ET, up $16.93 from the prior close. Depending on the data feed, the gain hit as high as 3.8%. Early-session volatility accounts for the variation.
Dell's 52-week low sits near $110. Today it traded roughly five times that level—the same company that once built laptops.
What happened at the open?
Buying pressure arrived at the bell. The stock advanced faster than typical. Given that Dell reached a 52-week high of $595 earlier this year, today's move appears aimed at testing that peak again.
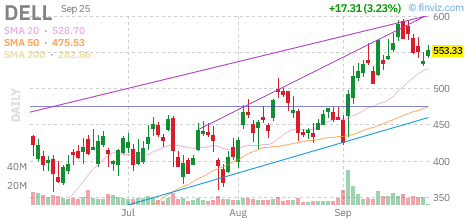
The chart shows recent consolidation followed by a bounce higher today. Whether this is a one-day rebound or a trend resumption remains unclear.
| Metric | Value |
|---|---|
| 9/25 morning move | +3.16% to +3.80% (by feed) |
| 52-week range | $110.22–$595.51 |
| P/E ratio | ~31x |
| Wall Street avg. target | ~$577–$580 |
Was there a specific catalyst today?
Honestly, no. Dell issued no new press releases or SEC filings on September 25. Instead, a broad bid appeared across semiconductor and technology stocks as investor flows favored AI-related names. Dell rode that sector momentum.
The deeper backdrop is Dell's early-September earnings announcement, which continues to echo. Analyst price-target upgrades have followed steadily since then, and today's move likely extends that trend. Still, pinning this specific intraday move to a single event would be imprecise.
What is Dell actually selling now?
Dell was built on PCs and notebooks. That is no longer the revenue driver. Servers and storage have become the center of gravity.
Orders for AI servers have exploded in particular. Last quarter alone, Dell booked $60.9 billion in new AI server orders. The backlog—unfilled orders on the books at quarter-end—reached $95 billion. To put that in perspective: it equals the annual defense budget of a mid-tier nation.
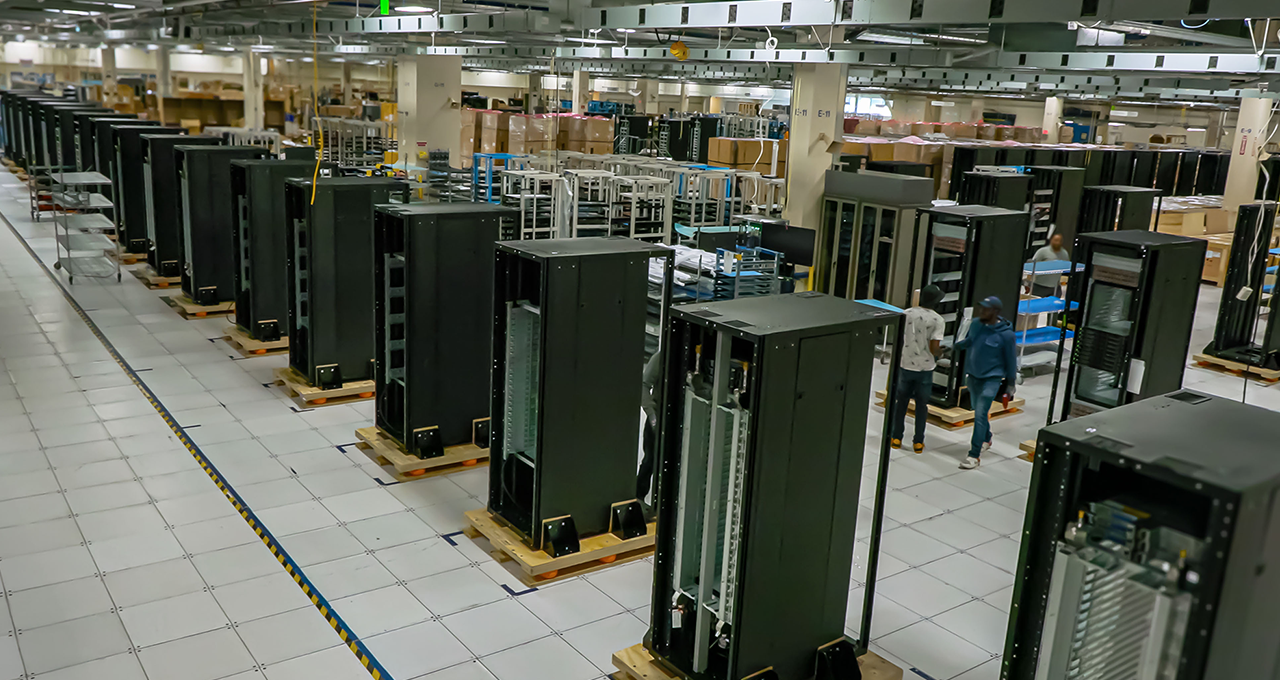
As these orders convert to revenue, the quarter produced $47 billion in total sales—up 58% year-over-year and the largest quarterly total in company history.
Management confidence has shifted higher. The company raised fiscal 2027 revenue guidance by $25 billion to $192 billion—well above prior forecasts.
What do analysts say?
On September 10, Evercore analyst Amit Daryanani reiterated a buy rating and raised his price target to $650—implying 20% upside from current levels.
Broader Street consensus is similar. The average target among 29 analysts tracked by S&P Global is $577. The consensus rating leans bullish. That said, a rising price target does not mean the stock is cheap. Targets tend to rise along with the share price, especially for names that have already moved sharply.
What to watch
Valuation is the first consideration. At roughly 31x P/E, the multiple is not modest for a traditional hardware manufacturer. The AI server growth narrative appears to justify the premium. If that narrative cracks, valuation could follow.
Competition is the second. Supermicro and HPE are competing for the same AI server wallet. A large backlog is not the same as margin-accretive execution. Rising input costs and supply-chain pressure could compress profitability.
Speed of advance is the third. Dell stock has risen roughly five-fold in 52 weeks. Such moves breed outsized volatility in both directions. Today's 3% jump could just as easily reverse.
How to frame the moment
Dell is in the midst of a corporate identity shift: from hardware vendor to AI infrastructure supplier. The numbers already reflect that transition. Earnings and share price are pointing the same direction—a rare alignment.
Today's 3% move, however, belongs more to sector momentum than to Dell-specific developments. The focal point narrows to one data point: next quarter's earnings (fiscal 2027 Q3). Can management hit its guided $49 billion in revenue and $6.50 in earnings per share? If those figures fail to materialize, current optimism could evaporate just as quickly.
As long as the numbers hold up, this rally has a foundation. The moment they don't, the story changes entirely.
Dell is a U.S.-listed company. This analysis is factual and does not constitute a buy or sell recommendation. Investment decisions and outcomes are the reader's responsibility.
#Dell #DELL #AI servers #data center #Nvidia #semiconductors #server stocks #stock surge #Michael Dell #price target #analyst #earnings #AI infrastructure #Nasdaq #U.S. market #tech stocks
댓글
댓글 쓰기