[U.S. Market Brief] U.S. 10-Year Yield Hits 24-Year High at 5.34 percent; SK Hynix ADR Surges 5 percent
Good Friday morning, October 2, 2026. Overnight in New York, the U.S. 10-year Treasury yield climbed to 5.342 percent intraday—the highest level in 24 years since April 2002. Stocks fell early, but reversed to positive across all three major indices as yields retreated.
Semiconductors were even stronger. The Philadelphia Semiconductor Index rose 1.59 percent, with SK Hynix American Depositary Shares (ADRs) up 5.08 percent. The KOSPI Index, meanwhile, already closed yesterday at 6,971.35, up 1.95 percent. Today's Korean market opens in the tension between whether additional tailwind follows yesterday's semiconductor gains or whether the 24-year high in rates weighs on sentiment.
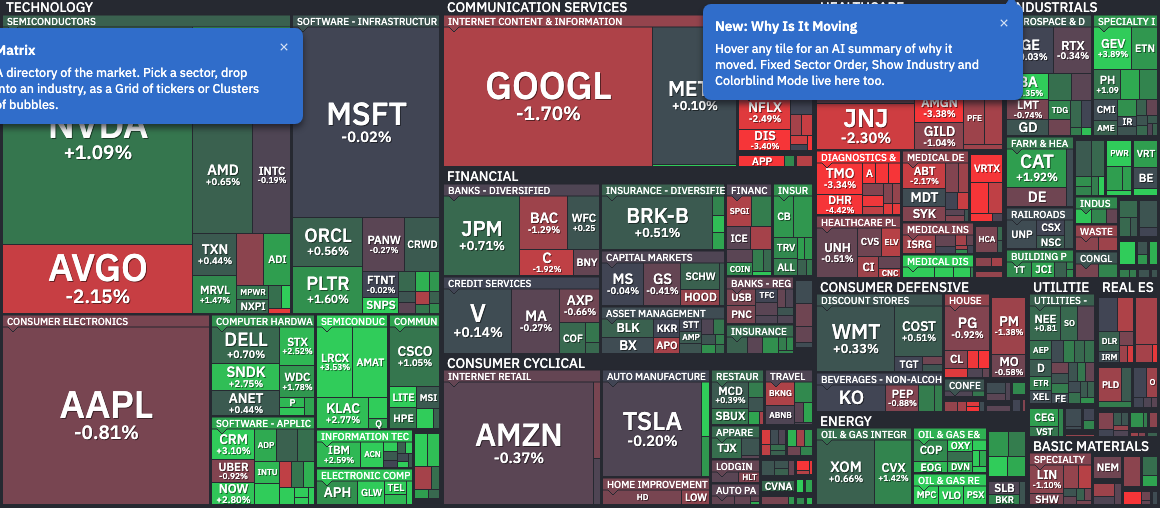
U.S. market heatmap, October 1 (finviz): Green marks gainers, red marks decliners
U.S. three major indices close slightly positive after intraday selloff
October 1 (U.S. time) closing figures:
| Index | Close | Pct Change | Intraday Low |
|---|---|---|---|
| Dow | 50,926.56 | +0.04% | — |
| S&P 500 | 7,666.45 | +0.19% | 7,616.78 |
| NASDAQ | 26,871.60 | +0.04% | 26,733.89 |
| Philadelphia Semiconductor Index | 12,829.00 | +1.59% | 12,587.34 |
The headline numbers look flat. Intraday was different. The S&P 500 fell as low as 7,616.78, some 0.45 percent below the prior close. It closed up 0.19 percent, recovering more than 0.6 percentage points from low to finish.
The selloff was driven by rising yields and inflation concerns. The Institute for Supply Management's September manufacturing purchasing managers' index (PMI) came in at 54.5, with manufacturers reporting sharply elevated costs. If inflation picks up, the Fed will raise rates. Markets priced that scenario in immediately.
The recovery came on a single comment from the Fed's number two. Federal Reserve Vice Chair Philip Jefferson said in a University of Virginia speech that colleagues may "take more time" reaching individual conclusions. Markets read this as the Fed won't rush to hike rates. CME FedWatch probability of an October rate hike fell to 28.2 percent by afternoon, down from 34.9 percent at the previous close.
Accenture stood out among individual stocks. Shares jumped 15.78 percent after the consulting giant posted earnings above expectations and raised full-year revenue guidance. A near-16 percent single-day move in a major IT consulting stock is uncommon. MoneyToday noted the results improved investor sentiment across IT and software broadly.
Mega-cap tech stocks were mixed. In the heatmap above, Nvidia was up 1.09 percent, Alphabet up 1.70 percent, and Apple down 0.81 percent. There was no one-way direction.
Micron swung 7 percent intraday, from -4 percent to +3 percent
For Korean investors, this number matters most: The Philadelphia Semiconductor Index closed at 12,829.00, up 1.59 percent. The prior day was essentially flat, down 0.54 points.
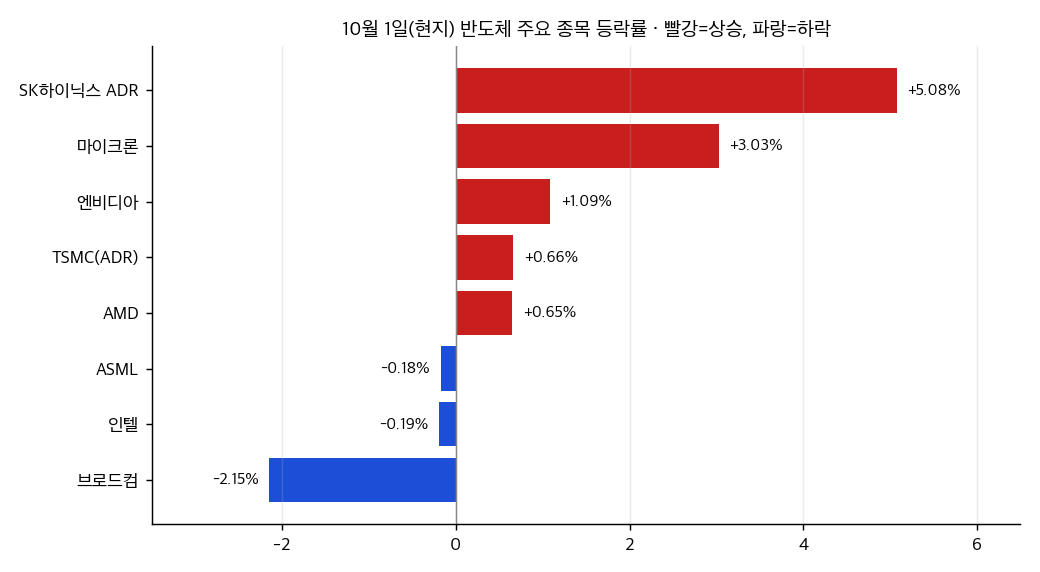
October 1 (U.S. time) semiconductor sector performance and leading stocks; SK Hynix ADR figure via MoneyToday
Micron reported fiscal Q4 revenue of $5.423 billion and guided fiscal Q1 revenue to $6.15 billion, both above consensus estimates.
Yet the stock fell as low as $1,022.90 the next day, near -4 percent from the prior close. It closed at $1,097.39, up 3.03 percent. The intraday range exceeded 7 percent.
Everyone knew the results were good. The question was how much was already priced in. Early buyers thought the gains were already baked in; afternoon buyers after rates retreated thought there was more upside. That's one day's reading, subject to revision.
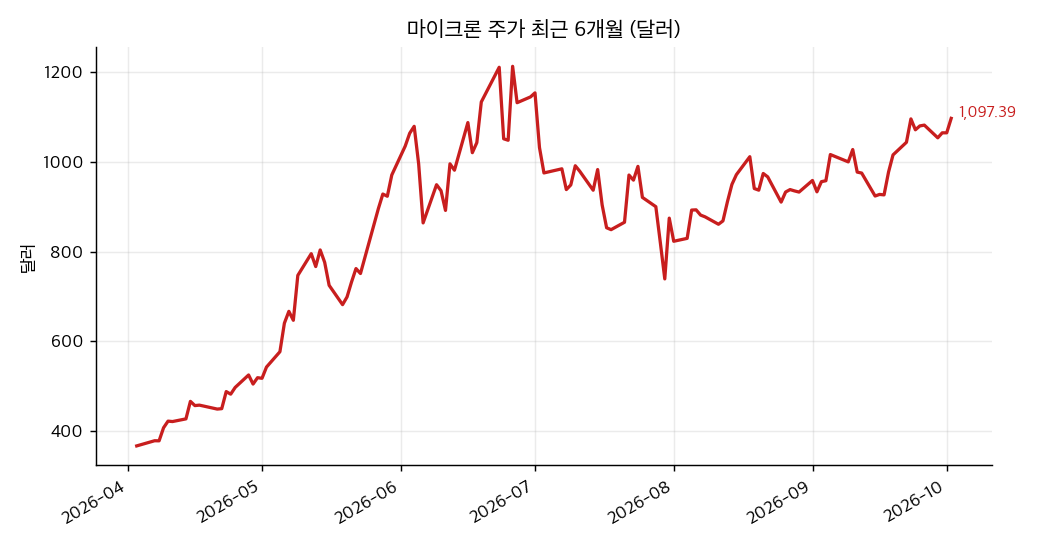
Micron six-month price chart (Yahoo Finance daily close)
SK Hynix ADRs rose 5.08 percent, outperforming Micron's 3.03 percent. As a fellow memory chipmaker, SK Hynix is often compared against Micron. Nvidia rose 1.09 percent, TSMC ADRs 0.66 percent, and AMD 0.65 percent. Broadcom was the laggard, down 2.15 percent, the biggest decliner among the semis shown. ASML and Intel were virtually flat, within 0.2 percent. It wasn't a uniform advance across the sector.
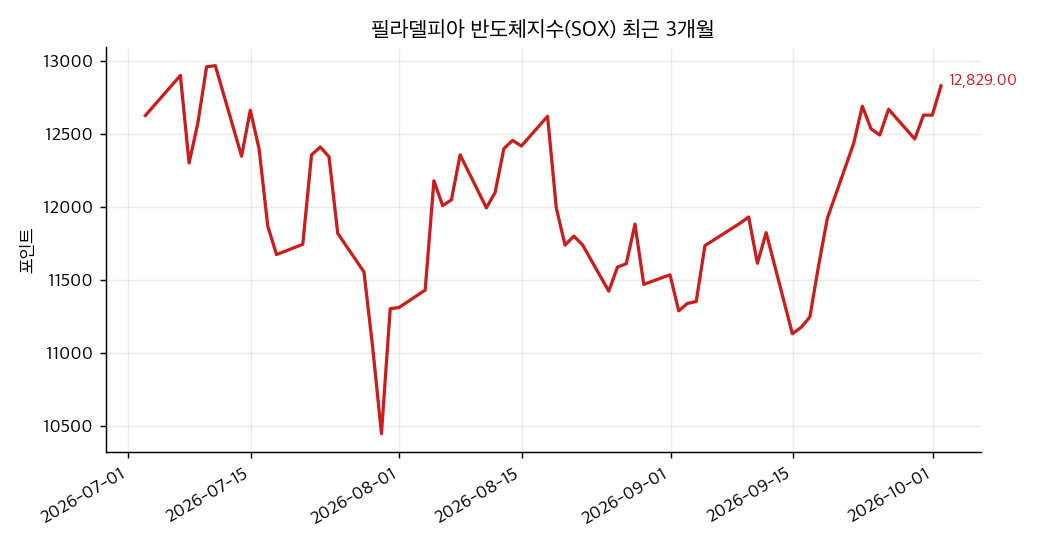
Philadelphia Semiconductor Index three-month price chart (Yahoo Finance daily close)
Yields retreated, yet caution lingers on the near term
The U.S. 10-year yield peaked at 5.342 percent intraday before settling around 5.24 percent. Yahoo Finance showed 5.237 percent at close. The 30-year yield came down slightly from 5.638 percent to 5.603 percent.
The decline doesn't mean rates are low. In early July, the 10-year was around 4.5 percent. In three months, it's risen more than 0.7 percentage points. Today's retreat pales next to that rise.
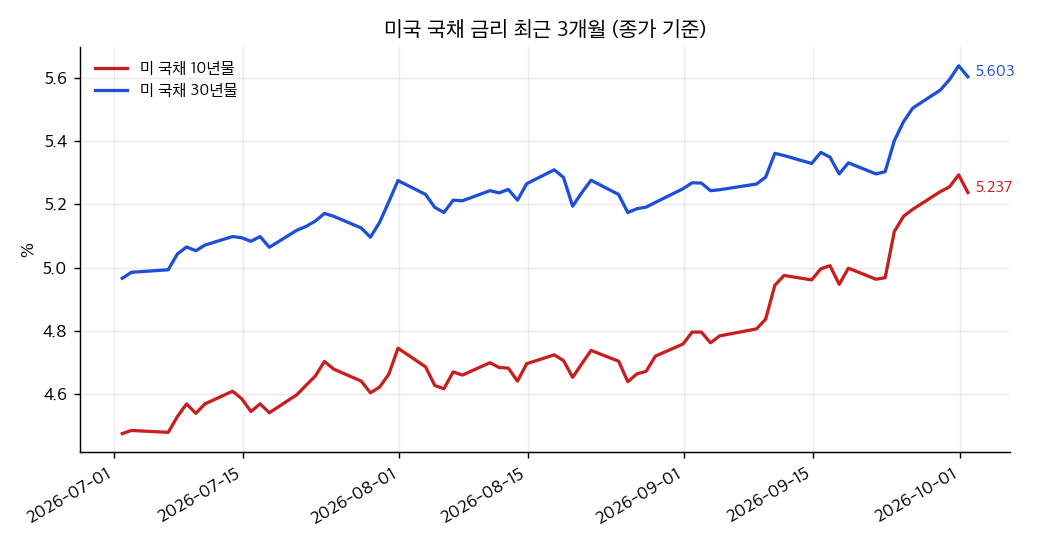
U.S. Treasury yields, 10-year and 30-year, three months (closing basis; intraday peak 5.342 percent not shown)
Higher rates increase the discount rate applied to stock valuations. Future earnings are discounted more heavily to present value. Growth stocks, whose profits are concentrated far in the future, are hit hardest.
Oil surged. December Brent crude rose 4.37 percent to $102.31 per barrel, and November WTI climbed 2.71 percent to $92.87. Brent is back above $100. Reports of China halting oil-product exports and the U.S. deploying additional forces to the Middle East widened supply concerns, according to reports.
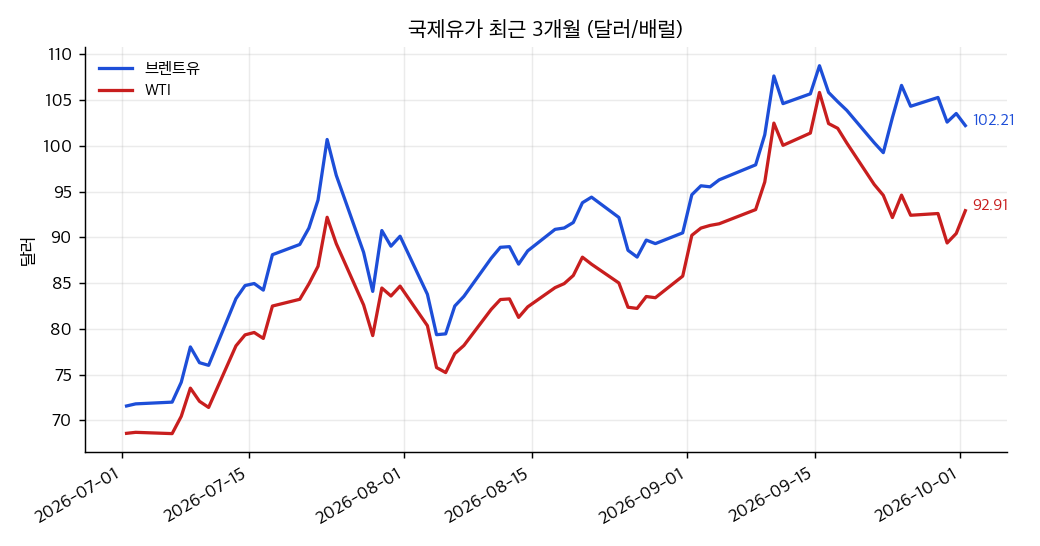
Brent crude and WTI, three months (Yahoo Finance front-contract closing basis)
The dollar strengthened. The Dollar Index, measuring the dollar against six major peers, climbed to 102.05, nearly 0.6 percent above the prior close. That's headwind for the won.
In Seoul's forex market, the dollar-won rate rose 2.7 won to 1,358.4 won as of 3:30 p.m. Foreign investors posted their fifth straight day of net selling on the KOSPI, offloading 548.1 billion won. The day before they sold more than 2 trillion won. They continued selling but at roughly one-quarter the prior volume.
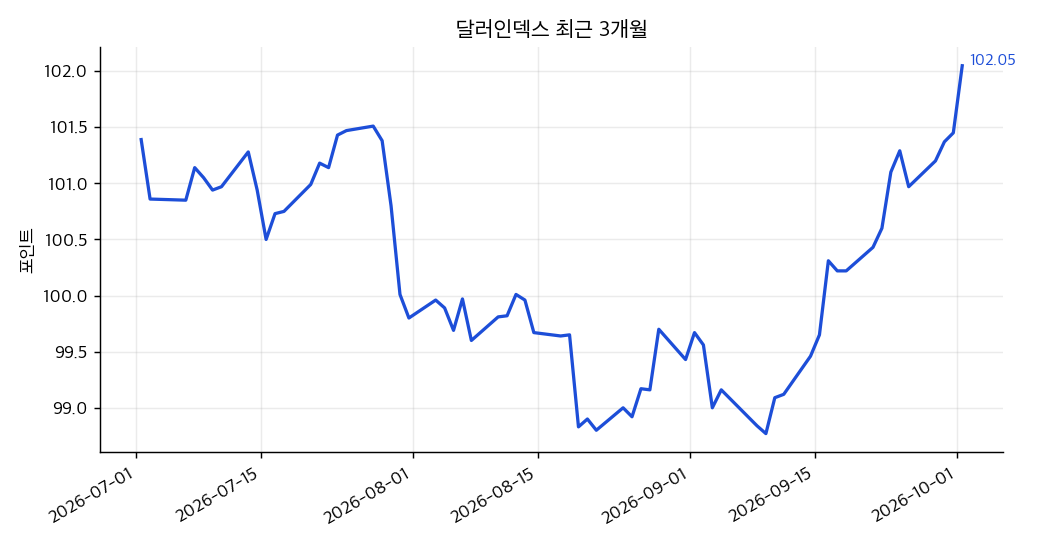
Dollar Index, three months (Yahoo Finance daily close)
Asia opens strong; Japan Nikkei surges 3.30 percent on semiconductor optimism
Micron's results hit Asian markets first. Japan's Nikkei 225 closed up 3.30 percent at 68,956.72 yen. Laser Tech led gainers with 11.14 percent, followed by Advantest at 9.78 percent and Tokyo Electron at 6.47 percent. Chip-equipment stocks led the rally.
| Market (Oct. 1) | Close | Pct Change |
|---|---|---|
| Japan Nikkei 225 | 68,956.72 | +3.30% |
| Taiwan TAIEX | 48,353.49 | +0.86% |
| China Shanghai Composite | Closed | National Day holiday |
| KOSPI | 6,971.35 | +1.95% |
Taiwan's TAIEX gained 0.86 percent to 48,353.49. TSMC rose 1.21 percent and United Microelectronics (UMC) jumped 4.53 percent. However, concerns about U.S. long-term rates capped the advance.
China's Shanghai Composite and Hong Kong markets were closed for the National Day holiday. On the last trading day, September 30, Shanghai closed at 3,842.20, up 0.31 percent. China's official September manufacturing PMI at 50.1 marked a return to expansion territory for the first time in two months.
What to watch today in Seoul: Momentum on day two?
What's tricky about today's Korean session: Micron's positive catalyst was largely already priced into yesterday's KOSPI close. Yesterday, Samsung Electronics closed up 2.79 percent at 276,000 won and SK Hynix up 3.21 percent at 1,833,000 won. News that September semiconductor exports exceeded $60 billion for the first time ever came that same day.
So adding last night's 1.59 percent semiconductor index move and 5.08 percent SK Hynix ADR move directly to today's opening may not be straightforward. The MSCI Korea ETF (ticker: EWY) rose 1.82 percent overnight. That likely reflects lagging exposure to yesterday's KOSPI gains.
Here's what to watch today:
| What to Watch | Last Night's Move | Today's Key Level |
|---|---|---|
| Semiconductor momentum (day two) | SOX +1.59%; SK Hynix ADR +5.08% | Whether Samsung Electronics and SK Hynix hold yesterday's gains through morning |
| Foreign investor flow | Fifth consecutive net selling; 548.1 billion won yesterday | Does selling extend to sixth day? Volume shrinking further? |
| Interest rates | U.S. 10-year hit 5.342% intraday, settled around 5.24% | Korean 10-year yield direction (closed yesterday at 4.436%) |
| Oil | Brent $102.31 (+4.37%) | Divergence between refiners/chemicals and airlines/transportation? |
| U.S. employment report | September nonfarm payrolls; Korea time tonight at 9:30 p.m. | Consensus 88,000 payrolls; unemployment at 4.1% vs. expectations |
Oil has divergent sector effects. Higher crude benefits refiners as product prices rise. Airlines and transporters face higher fuel costs. Chemicals on the KOSPI fell 1.12 percent yesterday. Today's reaction with oil surging higher will be telling.
The U.S. employment report comes after the Korean market closes. Whether foreign investors wait for the report or step up semiconductor trading will show in intraday flows. I can't predict that. The first 30 minutes after the open will tell.
In three lines: last night's story
U.S. 10-year yields hit a 24-year peak and retreated. In that window, the SOX rallied 1.59 percent and SK Hynix ADRs 5.08 percent. But Brent reclaimed $100 and the dollar strengthened.
Today the KOSPI opens at yesterday's 1.95 percent gain. Whether today brings an additional tailwind or if rates, oil, and the dollar weigh on sentiment. Foreign investor flows in the first hour will tell. Tonight's employment report sets up Monday's action.
This article summarizes publicly available prices and reported data and does not constitute investment advice or a recommendation to buy or sell any security. Investment decisions and their outcomes remain the reader's responsibility.
#KOSPIIndex #USMarkets #USStocks #NASDAQ #SOX #Micron #SKHynix #SKHynixADR #SamsungElectronics #USYields #10YearYield #Crude #Brent #DollarIndex #FX #Jefferson #FederalReserve #Accenture #Nikkei #USJobs #SemiStocks #ForeignSelling #MarketOutlook #MarketBrief #GlobalMarkets
댓글
댓글 쓰기